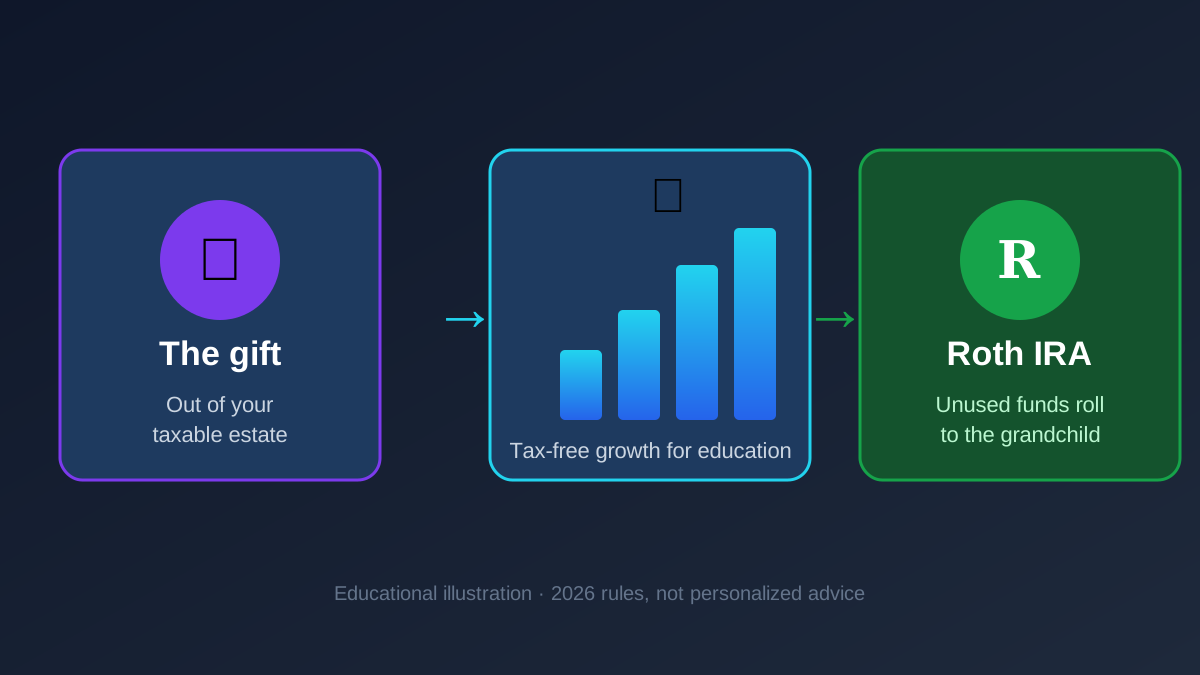
Why a 529 is an estate and legacy tool for grandparents
Praxion is built to answer one question first: will your own retirement hold up? Gifting comes after that. Retirement security comes first — your essential expenses, your health-care and long-term-care reserves, and your own long-term needs should be adequately covered before any money is earmarked for a grandchild. Once a plan is secure, many retirees look for a tax-efficient way to help the next generation, and a 529 education account is one of the cleanest tools available.
The reason it belongs in a retirement conversation is that a 529 is quietly an estate and legacy lever. A contribution is generally treated as a completed gift for gift-tax purposes, and 529s get special rules that keep the balance out of your taxable estate even though you keep control — you decide the investments, you can change the beneficiary, and you can even reclaim the money (paying tax and a 10% penalty on the earnings if you do). Few other vehicles combine “out of my estate” with “still under my control.” (One exception to know: a five-year election needs attention if you die before the period ends — see below.)
Order of operations
Fund your own retirement and health-care reserves first. A 529 gift is a use of surplus — money your plan shows you can give without putting your own security at risk. If you are unsure whether you have that surplus, model it before you gift.
The three tax advantages of a 529 plan
Tax-free growth
Earnings grow federally tax-free and come out tax-free when used for qualified education expenses — tuition, fees, books, and room and board.
State deduction (varies)
More than 30 states plus D.C. offer a state income-tax deduction or credit for contributions. A few offer none, and a handful give "tax parity" for any state’s plan. Check your own state.
Estate reduction
Contributions are generally completed gifts and 529s sit outside your taxable estate — even though you keep control. (A five-year election has an exception if you die within the window.)
The first two advantages are about the grandchild’s education cost. The third is about your estate — and it is where the gift-tax rules come in.
How to superfund a 529: five years of gifts in one
In 2026 you can give any one person up to $19,000 ($38,000 for a married couple splitting the gift) without touching your lifetime gift-tax exemption or filing anything. A 529 contribution is an exclusion gift like any other — but it comes with a feature no other gift has: a five-year front-load election.
Electing the five-year spread (reported on IRS Form 709) lets you treat one large contribution as if it were made evenly over five years. That means a single donor can put in up to five times the annual exclusion — $95,000 per grandchild, or $190,000 for a married couple — in one year, gift-tax-free. That lump sum then compounds tax-free for as long as it stays invested. Two trade-offs to weigh: any additional gifts to that same grandchild during the five years may exceed your remaining annual exclusion and start drawing on your lifetime gift-tax exemption; and if you die before the five-year period ends, the unused portion is added back to your taxable estate. For affluent grandparents managing estate size, that second rule is exactly why the timing of a superfund matters.
The 529-to-Roth IRA rollover: SECURE 2.0’s escape hatch
The biggest historical objection to funding a 529 was “what if they don’t go to college?” SECURE 2.0 added a meaningful answer. Starting in 2024, unused 529 funds can roll into the beneficiary’s Roth IRA, giving leftover money a tax-advantaged second life as retirement savings for your grandchild.
Two details matter before you count on this. First, the rollover lands in the designated beneficiary’s Roth IRA — the grandchild’s, not the grandparent-owner’s. Second, contributions (and their earnings) you made in the last 5 years are not eligible to roll — so a large contribution made shortly before a planned rollover can’t be moved yet. Because the annual rollover is also capped at the beneficiary’s Roth contribution limit (reduced by any other IRA contributions they make and by their earned income), moving the full $35,000 takes several years. Treat it as a long-term contingency against overfunding — not a guaranteed exit strategy. The upside: a gift you made for education can end up seeding a grandchild’s tax-free Roth account decades before they would otherwise open one.
Do grandparent-owned 529s affect financial aid (FAFSA)?
For years, advisors warned grandparents away from owning a 529 directly: a distribution counted as untaxed student income on the FAFSA and could cut need-based aid by as much as half the withdrawal. The FAFSA Simplification Act ended that. Beginning with the 2024–25 FAFSA, grandparent-owned 529 distributions are no longer reported as student income, and the form no longer asks about cash support from a grandparent.
In practice, a grandparent-owned 529 is now often the more aid-friendly choice, because the account is not a parent asset either. Aid formulas can still change, so treat this as the current federal rule rather than a permanent guarantee — and note that some private colleges use their own aid form (the CSS Profile), which may still ask.
When a 529 plan may not be the right move
A 529 is a strong tool for a specific goal — education — and the honest framing matters more than the sales pitch. It may not fit when:
- Your own plan isn’t secure yet. Money in a 529 is earmarked; pulling it back for your own needs triggers income tax plus a 10% penalty on the earnings.
- The child’s path is uncertain and you want full flexibility. The 529-to-Roth rollover and beneficiary changes soften this, but a taxable brokerage gift keeps every option open (at the cost of the tax shelter).
- Your state offers no deduction. The federal tax-free growth still applies, but part of the headline benefit is state-specific — and a few states even “recapture” a prior deduction on a non-qualified withdrawal.
- You may need the money for long-term care. A gift you might have to claw back is not a reserve. Keep your care buffer outside the 529.
None of these make a 529 a bad choice — they define where it fits. A 529 often works well when your retirement is funded, the education goal is real, and you want the money out of your estate but still under your control.
How much should you put in a 529?
The limits above are ceilings, not targets. The right amount is the smaller of two numbers: what your plan can spare, and what the education goal actually needs. Before choosing a figure, work through a few questions:
| Ask yourself | Why it matters |
|---|---|
| Is my own retirement fully funded? | Fund your plan first — a 529 gift should come from surplus, not from your security. |
| Do I have a long-term-care reserve? | A 529 is earmarked for education, not an accessible care reserve. |
| Is education the primary goal? | If flexibility matters more, a taxable gift or a trust may fit better. |
| How many grandchildren will I help? | Shapes an equitable plan across children and grandchildren. |
| Does my state give a deduction or credit? | Affects the net benefit — and a few states recapture it on non-qualified use. |
| Is superfunding right for my liquidity and estate? | Depends on cash on hand, gift timing, and estate goals. |
| Who should own the account? | Affects control and financial-aid treatment (see below). |
An illustrative example
A grandparent, age 65, retirement fully funded, with two grandchildren and about $100,000 of surplus earmarked for education. Four ways to deploy it — each a different balance of tax, growth, flexibility, and estate impact (illustrative, not a recommendation):
- $19,000/year (the annual exclusion) — stays inside the per-recipient exclusion with no Form 709 for a single or married giver, and keeps flexibility to redirect if plans change; slower to get money compounding.
- $95,000 superfund for one grandchild — maximum tax-free compounding and estate reduction now; uses five years of exclusion for that child and concentrates on one beneficiary.
- $50,000 per grandchild — an even split and a meaningful head start for both; within a single-year exclusion for a married couple (a single filer would file Form 709).
- A blend — e.g. $50,000 into 529s and $50,000 kept in a flexible taxable account for uncertainty; less tax shelter, more optionality.
There is no single right answer — it depends on your surplus, the children’s ages, and how much flexibility you want. Model your own plan first to see how much surplus it can safely spare.
Grandparent-owned vs. parent-owned 529
Who owns the account changes two things — control, and how it’s treated for financial aid. Neither is universally better; the right choice depends on how much control you want and how aid-sensitive the family is.
| Owner | Control | Financial aid (FAFSA) | Often fits when |
|---|---|---|---|
| Grandparent-owned | You keep full control — change the beneficiary or reclaim funds. | Distributions no longer count as student income (2024–25 FAFSA on). | You want control and estate reduction. Some CSS-Profile schools may still ask. |
| Parent-owned | The parent controls the account. | Counted as a parental asset (assessed at a low rate); distributions aren’t student income. | You prefer a predictable FAFSA treatment and are comfortable handing over control. |
529 vs. brokerage vs. trust vs. direct tuition
A 529 isn’t the only way to help. Each vehicle serves a different purpose — the goal is matching the tool to what you actually want to do, not declaring one universally best.
| Option | Main purpose | Key trade-off |
|---|---|---|
| Grandparent 529 | Education funding with retained control | Education-restricted; 10% penalty on non-qualified earnings |
| Parent 529 | Education funding | Different aid and control treatment |
| Taxable brokerage gift | Flexible gifting for any purpose | Taxable growth; no education tax shelter |
| Direct tuition payment | Pay a school directly once enrolled | Unlimited and gift-tax-free — but tuition only (not room/board), paid straight to the institution |
| Trust | Broader legacy control | Legal complexity and administration cost |
The direct-tuition route is underused: paying a grandchild’s tuition directly to the school is exempt from gift tax entirely (IRC §2503(e)), on top of your annual exclusion — useful once they’re actually enrolled.
Multiple grandchildren: the fairness question
With grandchildren of different ages, equal contributions don’t produce equal support — a dollar given to a 2-year-old has 16 more years to compound than one given to an 18-year-old. Equal initial dollars quietly favor the youngest. Common approaches:
- Equal initial contributions — simplest and feels fair, but the youngest ends up with the most growth.
- Equal projected value at 18 — contribute less for older grandchildren and more for younger ones, targeting a similar amount available for each.
- Fund by expected need — size each contribution to the child’s likely path (in-state vs. private, undergraduate vs. graduate).
- Separate education from inheritance — use 529s for education and let your broader estate plan handle overall fairness.
There’s no objectively correct split — the point is to decide deliberately rather than default to equal dollars.
How a 529 fits your retirement plan
Gifting to a grandchild is a legacy decision, and legacy sits alongside the other levers a good plan weighs — Roth conversions, the timing of Social Security, and how much of your estate passes as pre-tax versus tax-free dollars. The 529 question is really a surplus question: does your plan show room to give without weakening your own security?
Praxion models your retirement — income, taxes, withdrawals, and what you leave behind. It does not track 529 balances or run a college-savings projection; those live with your 529 plan provider. What it can tell you is whether you have the surplus to fund one in the first place, and how a legacy goal interacts with the rest of your plan.
See whether your plan has room to give
Build a picture of your retirement income, taxes, and legacy — then decide how much surplus you can direct to a grandchild’s future.
Build your retirement plan →Praxion Finance is a decision-support tool, not a registered investment adviser. This article is educational and not tax, legal, or investment advice.
529 plans for grandchildren: frequently asked questions
Can grandparents open a 529 plan for their grandchildren?
Yes. A grandparent can open and own a 529 with a grandchild as the beneficiary, and the grandparent stays in control of the account — including the ability to change the beneficiary or reclaim the funds (earnings on a non-qualified withdrawal are taxed as income plus a 10% penalty). Contributions are treated as completed gifts using the $19,000 per-beneficiary annual gift-tax exclusion ($38,000 for a married couple splitting the gift).
How much can you superfund a 529 in 2026?
A five-year front-load election lets one donor contribute up to five times the annual exclusion in a single year and treat it as spread evenly over five years — $95,000 per beneficiary, or $190,000 for a married couple — without using lifetime gift-tax exemption. You report the election on IRS Form 709. During those five years, additional gifts to that same beneficiary may exceed the remaining annual exclusion and would then draw on your lifetime gift-tax exemption; and if you die before the period ends, the unused portion is added back to your taxable estate.
Can a 529 roll over to a Roth IRA?
Under SECURE 2.0, a 529 open at least 15 years can roll unused funds into the Roth IRA of the plan's designated beneficiary — the grandchild, not the grandparent who owns the account — up to a $35,000 lifetime maximum. Each year's rollover is limited to that year's Roth IRA contribution limit ($7,500 for those under 50), requires the beneficiary to have earned income, and cannot include contributions (or their earnings) made to the 529 in the preceding 5 years. Treat it as a long-term contingency, not a guaranteed exit.
Do grandparent-owned 529s hurt financial aid?
Much less than they used to. Under the FAFSA Simplification Act (effective with the 2024–25 FAFSA), distributions from a grandparent-owned 529 are no longer reported as untaxed student income, which had previously reduced aid eligibility. The FAFSA also no longer asks about cash support from a grandparent.
What happens to leftover 529 money if the child does not go to college?
You have several options that avoid the penalty: change the beneficiary to another eligible family member (including yourself), use up to $10,000 (lifetime, per borrower) toward the beneficiary's student loans, apply funds to a qualified apprenticeship or to K–12 expenses (the K–12 limit rose to $20,000 per beneficiary per year in 2026, and eligible K–12 costs were broadened beyond tuition), or roll unused funds to the beneficiary's Roth IRA (up to $35,000 lifetime). Only a non-qualified withdrawal is penalized — income tax plus a 10% penalty on the earnings portion (not on your contributions).
Can a grandparent contribute $100,000 to a 529?
Yes, without gift tax — using the five-year election. The annual gift-tax exclusion is $19,000 per recipient ($38,000 for a couple), so a single $95,000 contribution (or $190,000 for a couple) can be spread over five years on IRS Form 709 and stay gift-tax-free. A contribution above the five-year cap isn't prohibited — it simply draws on your lifetime gift-tax exemption and is reported on Form 709. 529 plans also have a per-beneficiary lifetime aggregate limit set by each state's plan (commonly $500,000+).
Is it better for a grandparent or a parent to own the 529?
It depends on control and financial aid, and there is no universally better choice. A grandparent-owned 529 keeps you in control (you can change the beneficiary or reclaim funds), and since the 2024–25 FAFSA its distributions no longer count as student income. A parent-owned 529 is reported as a parental asset on the FAFSA (assessed at a low rate) and is the default for most families. Some private colleges use the CSS Profile, which may still ask about grandparent accounts.
Can a grandparent change the beneficiary of a 529?
Yes. As the account owner, a grandparent can change the beneficiary to another eligible member of the current beneficiary’s family (a sibling, cousin, the grandparent, and others). It is tax-free when the new beneficiary is in the same or an older generation. Moving to a younger generation (for example child → grandchild) is treated as a gift from the old beneficiary to the new one and can raise gift and generation-skipping transfer (GST) tax issues, so get advice before a change that moves down a generation.
Should a grandparent use a 529 or a trust?
They serve different purposes. A 529 is purpose-built for education — simple, low-cost, tax-free for qualified education expenses, and largely out of your estate while you keep control. A trust is a broader legacy vehicle for non-education goals, spending controls, or complex family situations, at the cost of legal and administrative complexity. Many families use a 529 for the education slice and a trust (or other assets) for the rest of a legacy plan.
Sources & Further Reading
- IRS: Frequently Asked Questions on Gift Taxes — annual exclusion and Form 709 rules
- IRS: About Form 709 (Gift Tax Return) — the five-year 529 front-load election
- SECURE 2.0 Act (H.R. 2954) — 529-to-Roth rollover provisions
- IRS Publication 970: Tax Benefits for Education — 529 qualified expenses, K–12 and distribution rules
- Federal Student Aid: FAFSA Simplification — treatment of grandparent 529 distributions
- Your state’s 529 plan documents and state tax authority — the authoritative source for your state’s deduction/credit, aggregate limit, and any recapture rules.
- Savingforcollege.com: 529 contribution and superfunding limits — state-by-state deduction detail (secondary reference)
Tax rules and education benefits change. This article was reviewed on September 18, 2026 against available IRS and federal guidance; verify current rules with the primary sources above (or a tax professional) before acting.